
Our view
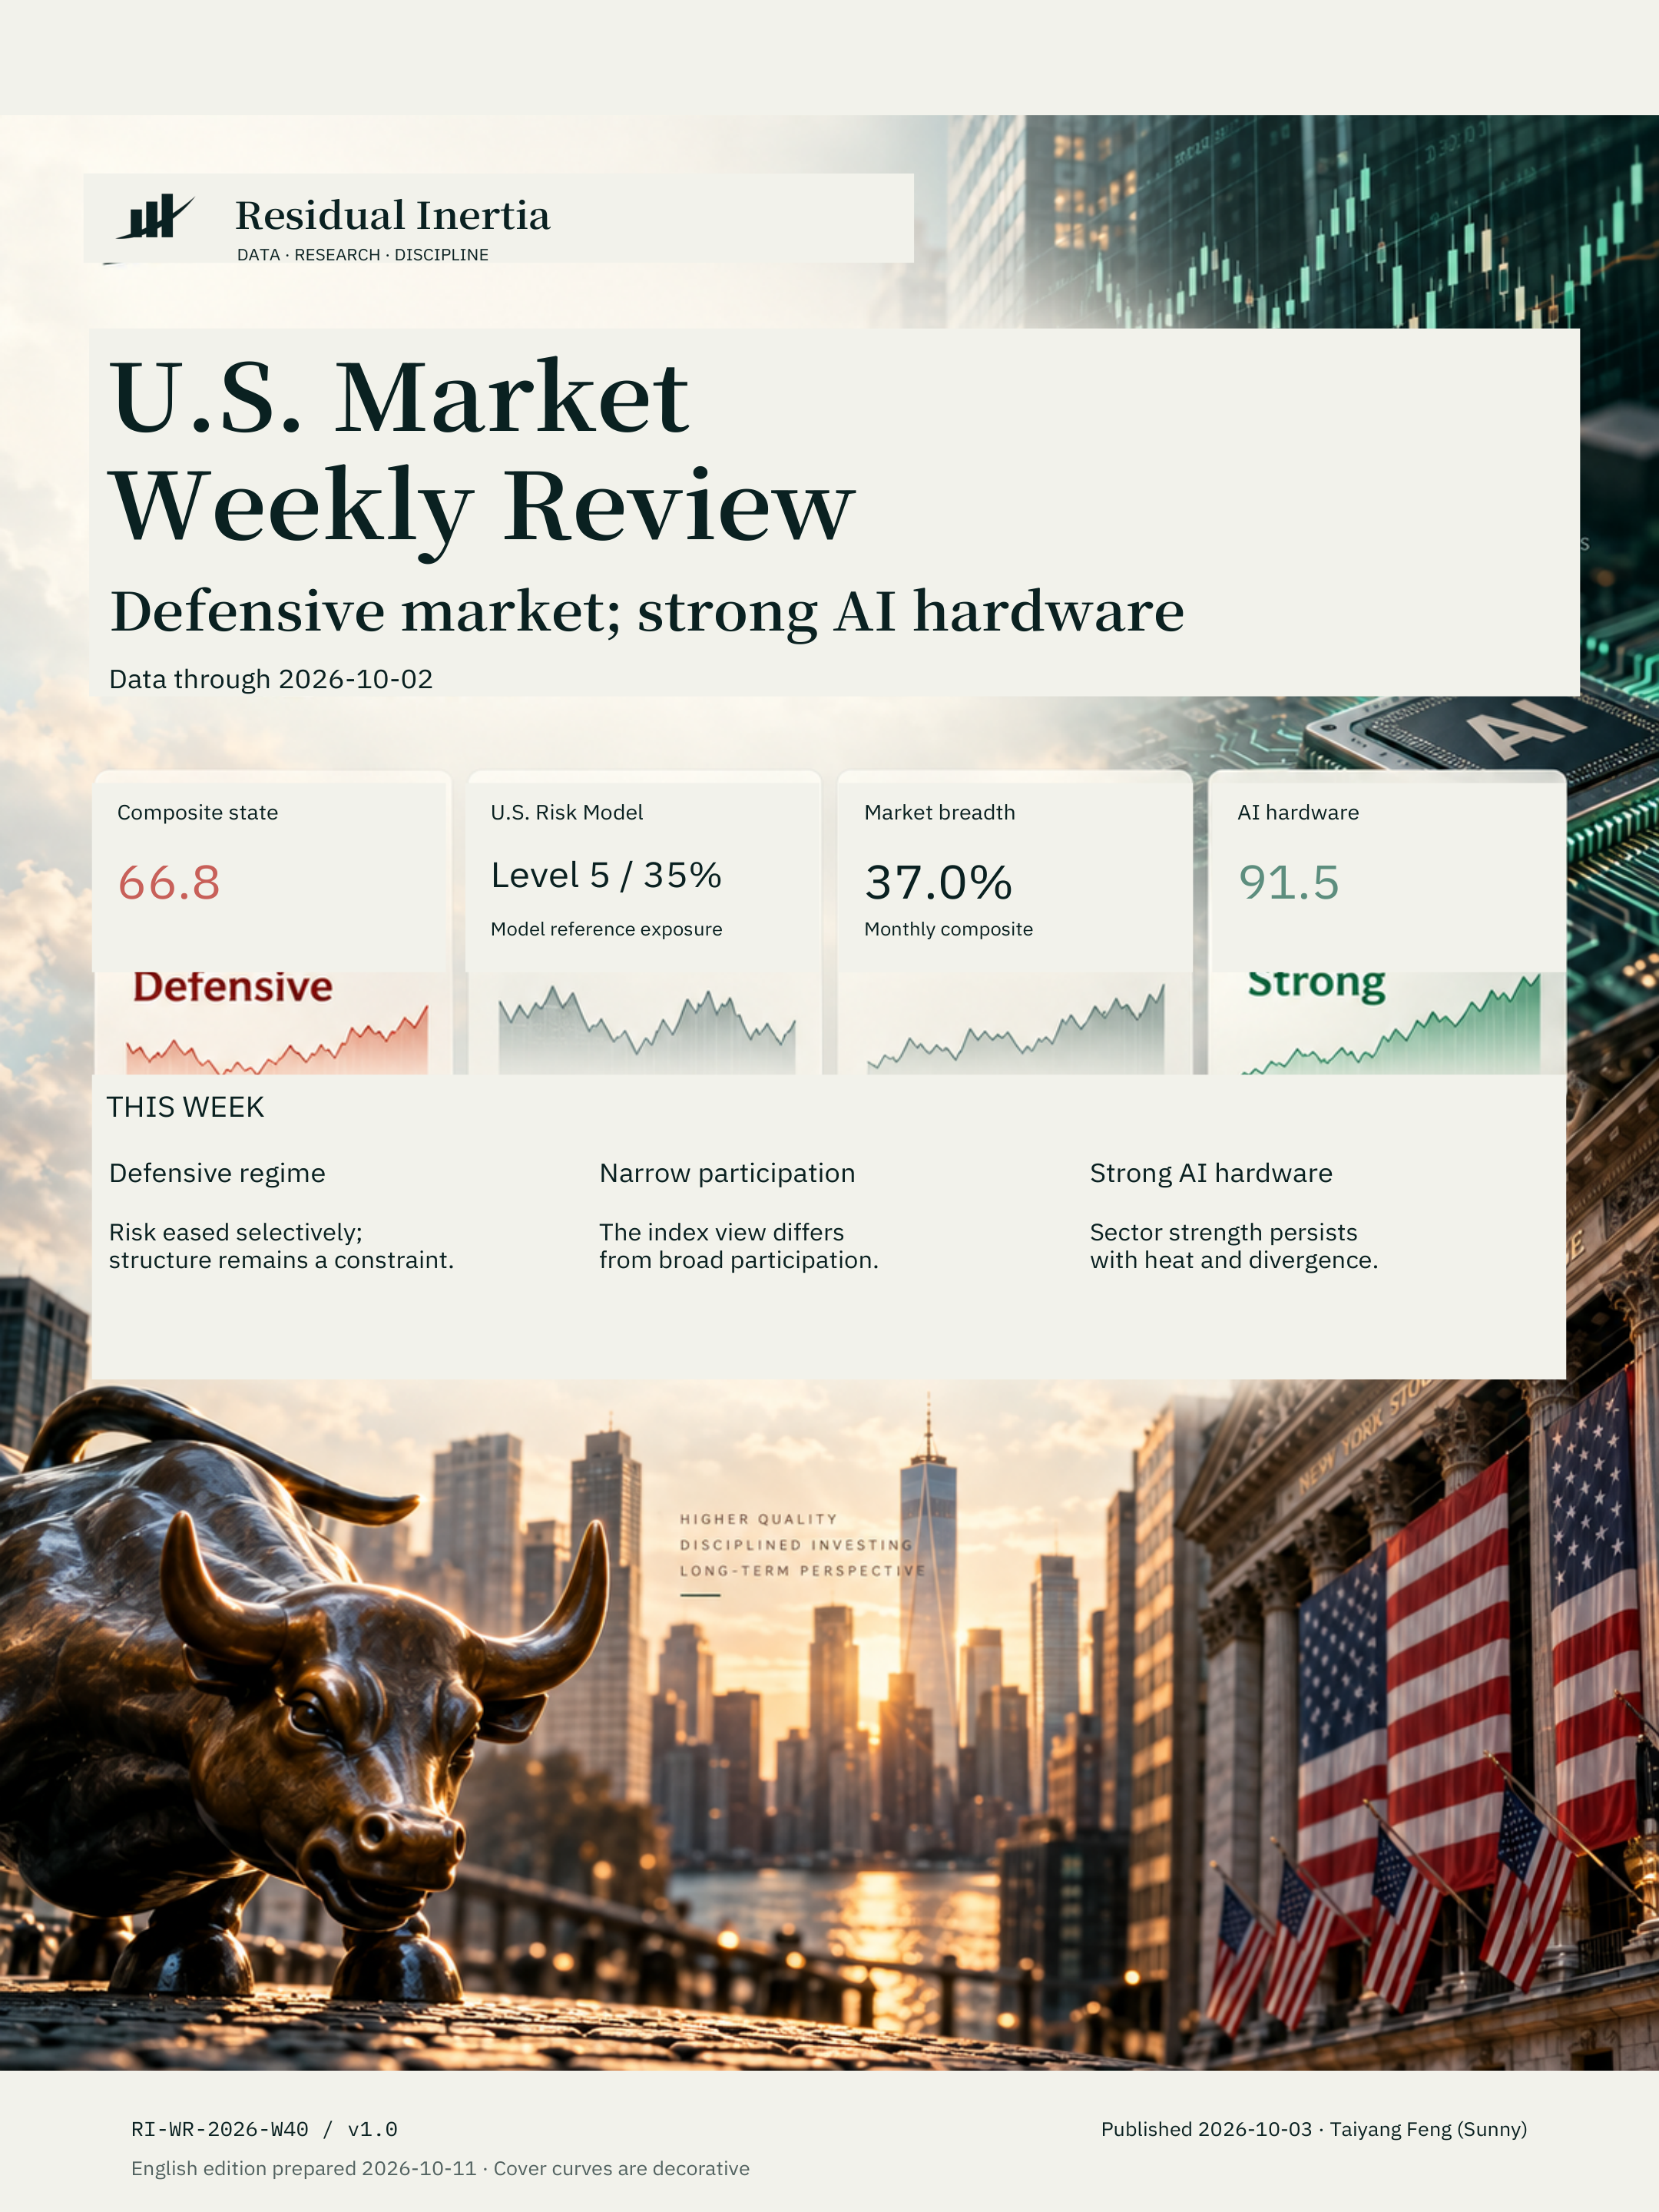
The composite regime score reached 66.8 (Defensive). The October 2 weekly signal is Level 5 with a 35% reference exposure, effective October 5. AI hardware scored 91.5 (Strong); SMH gained 14.12% over 20 trading days. Sector strength coexists with a defensive broad-market reading.
Author: Taiyang Feng
Report ID: RI-WR-2026-W40 · v1.0
Broad-market risk and sector strength
In the frozen dashboard data, five-trading-day price changes were -0.22% for SPY, +0.68% for QQQ and +3.96% for SMH. The same-vintage composite score rose from 63.77 on September 25 to 66.82 on October 2, moving from Caution to Defensive. Participation risk was 75.0, fragility 92.6, market risk 63.7 and financial stress 36.0. The October 2 weekly signal is Level 5 with a 35% reference exposure, effective October 5. These are model readings, not the author's holdings.[1][2]
What the 37.0% breadth figure means
The dashboard home figure is the simple mean of two September month-end ratios: 41.47% above the 200-day moving average (2,446/5,898) and 32.60% outperforming the SPY benchmark proxy over 12 months (1,863/5,715). Their average is 37.04%. The October 2 daily 200DMA estimate is separately 42.03% (2,449/5,827). The monthly figures use the Massive extension; they are not described as official CRSP observations. Different metrics and denominators prevent treating 37% to 42% as a five-point improvement.[1]
AI hardware: strong, with heat and divergence
The composite scored 91.5 (Strong), with demand momentum 100.0, supply-chain confirmation 95.4, leadership breadth 81.2 and relative risk appetite 90.4. Crowding/heat at 81.5 and divergence fragility at 69.6 are risk measures, so higher is worse. SMH's 20-trading-day gain of 14.12% exceeded QQQ's 4.45% and SPY's -0.46% by 9.67 and 14.57 percentage points. In the 28-stock monitored universe, 25 stocks were above each of the 20-day and 50-day averages (89.3%). These are sector measures, not broad-market 200DMA breadth. AMD, TER and MRVL led the monitored universe over 20 days, gaining approximately 39.0%, 32.6% and 30.4%. A high composite score does not imply a low entry cost or continuing gains. Watch whether strength spreads as heat and divergence ease.[1][2]
Rates: the answer depends on the window
As of October 1, the ACM 10-year fitted yield was 5.217%, comprising a 4.312% expected-average-short-rate component and a 0.905% term premium. Between September 1 and October 1, it rose 34.99 bp: 22.42 bp from the expected-rate component and 12.58 bp from the premium. Over three months, the premium contributed slightly more (36.23 bp versus 32.70 bp; total 68.93 bp). The expected-rate component accounted for approximately 64% of the one-month change; the term premium also rose. Rising long-end rates may increase valuation pressure, but this report does not identify an independent causal effect on equity returns. Expected rates contributed more over six months (60.33 versus 22.41 bp) and one year (75.90 versus 29.32 bp). These are model decompositions, not traded yield quotes or forecasts of the next FOMC decision.[3]
Financial conditions and what to watch
The latest available NFCI and ANFCI observations, dated September 25, were -0.548 and -0.574. Both indicate looser-than-average conditions under their respective definitions; their 0.026 difference alone does not establish tightening.[1][4] Watch whether daily breadth improves alongside prices, participation and fragility ease, and AI hardware strength persists while heat and divergence cool.
Version, methods and limitations
Published October 3, 2026. Equity/model cutoff: October 2; ACM: October 1; NFCI/ANFCI: September 25. The composite uses the dashboard's four-pillar rolling-percentile/equal-weight method; thresholds are <35 Constructive, 35-<50 Neutral, 50-<65 Caution, 65-<80 Defensive and >=80 Stress. The legacy score of 60.3 uses a different method. The previously published September 26 report retains its historical score of 63.36; this report's same-vintage September 25 observation is 63.77. Revisions are not treated as market changes.
Five- and 20-day returns are dashboard adjusted-price changes, not independently reconstructed dividend-reinvestment returns or strategy performance. Month-end breadth coverage was approximately 92.3% for the moving-average measure and 91.7% for the outperform measure. Breadth coverage and denominators vary; the AI sample contains only 28 stocks. Factor crowding dates differ: September 30 for the long-short ex-market variant, August 31 for beta-adjusted long-only. The screenshot's standalone WQS card labeled October 31 is not cited as an already observed current reading; the exported composite is retained without re-estimation. The English cover localizes the author-supplied artwork; its curves remain decorative. Body charts use the original frozen inputs.
Disclosure
Prepared by Residual Inertia | 余势, author Taiyang Feng (Sunny), for research and information only. This is not investment advice. Reference exposure is not an actual-account allocation. The author's holdings and conflicts are not disclosed in this report. Historical results do not guarantee future performance.
Sources & Limitations
Frozen dashboard outputs, same-vintage model history and New York Fed ACM data. English cover localizes the author-supplied artwork; the original Chinese cover is retained.
- [1] RI frozen report inputs
- [2] Massive adjusted-price methodology
- [3] New York Fed ACM Treasury Term Premia
- [4] Chicago Fed NFCI/ANFCI methodology
For research purposes only. Not investment advice. Past performance does not guarantee future results.